The 4-3-2-1 Rule: A Simple Guide to Commercial Property Valuation
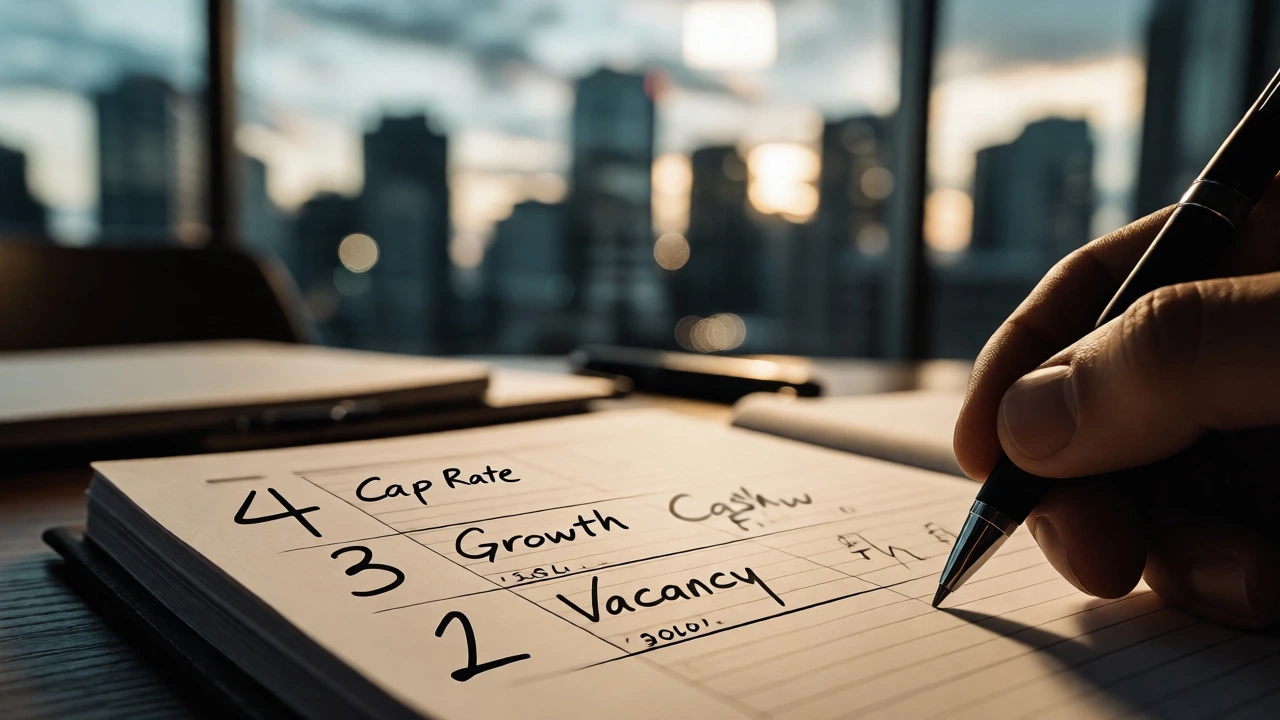
4-3-2-1 Commercial Property Valuation Checker
Use this tool to quickly sanity-check a commercial deal against the standard institutional investor heuristic. Enter your estimated metrics below.
Waiting for input...
Waiting for input...
Waiting for input...
Waiting for input...
Enter metrics above to generate a preliminary assessment based on the 4-3-2-1 rule.
Ever looked at a spreadsheet for a commercial building and felt like the numbers were speaking a foreign language? You see Net Operating Income (NOI), capitalization rates, debt service coverage ratios, and your head starts to spin. But there’s a shortcut that seasoned investors use to sanity-check a deal in seconds before they even open their calculator. It’s called the 4-3-2-1 rule. This isn’t a strict law of physics, but it is a powerful heuristic-a mental model-that helps you quickly assess if a property is priced correctly relative to its income potential.
Think of the 4-3-2-1 rule as a triage tool. When you’re scanning dozens of listings or analyzing a complex multi-tenant office park, you don’t have time for deep-dive discounted cash flow models on every single asset. You need a quick filter. The rule breaks down the relationship between price, income, and risk into four simple components. If a deal fits this pattern, it’s likely fairly valued. If it doesn’t, you know exactly where to dig deeper. Let’s break down what those numbers actually mean and how you can use them to protect your capital.
Decoding the Numbers: What Does 4-3-2-1 Actually Mean?
The name sounds cryptic, but the logic is straightforward once you map each number to a specific financial metric. Here is the standard interpretation used by institutional investors and private equity firms:
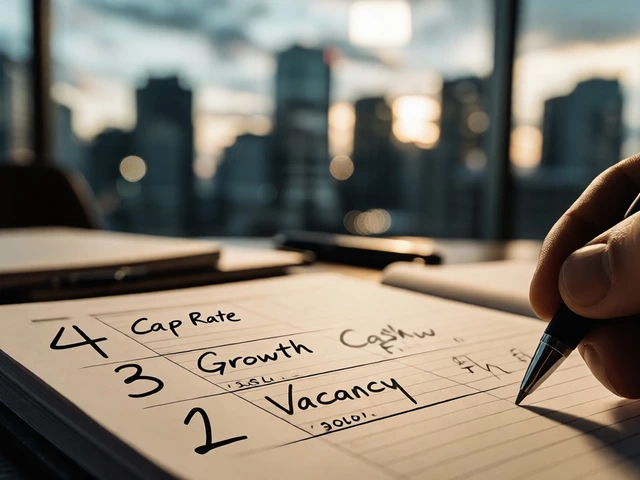
- 4% Cap Rate Floor: The first number refers to the minimum acceptable capitalization rate. In many stable markets, investors often look for a yield of at least 4% to justify the illiquidity and management effort of owning physical real estate versus buying stocks or bonds. If the cap rate drops below 4%, the price is getting expensive relative to the income it generates.
- 3% Annual Growth Target: The second number represents the expected annual growth in rental income or net operating income. Real estate is an inflation-hedge asset class. Investors typically aim for rents to grow by about 3% per year, which roughly tracks with long-term inflation expectations and wage growth. If rents are flat, the math changes significantly.
- 2% Cash-on-Cash Return Buffer: The third number is about immediate cash flow. After paying all expenses and debt service, do you want to see money left over? Many conservative investors require a positive cash-on-cash return of at least 2% just to cover opportunity costs and provide a safety margin against unexpected repairs or vacancies.
- 1% Vacancy & Credit Loss Allowance: The final number accounts for reality. No building is ever 100% occupied forever, and not every tenant pays on time. A prudent underwriting assumption includes a 1% deduction from gross potential income to account for vacancy loss and credit bad debts. Ignoring this leads to overly optimistic projections.
This framework forces you to balance three competing desires: high current income (cap rate), future appreciation (growth), and safety (cash buffer and vacancy allowance). It stops you from chasing "shiny object" deals that look great on paper but fail when you factor in real-world friction.
Why This Heuristic Works for Commercial Assets
You might ask, why bother with a rough estimate when we have sophisticated software? Because speed saves money. In competitive markets like Auckland’s CBD or major hubs like Sydney and Melbourne, good deals go under contract fast. If you spend three days modeling one property, someone else will buy it while you’re still adjusting your discount rate.
The 4-3-2-1 rule works because it aligns with the fundamental economics of commercial real estate. Unlike residential homes, where value is often driven by comparable sales (what did the neighbor sell for?), commercial property value is driven almost entirely by income. The formula is simple: Value = NOI / Cap Rate. By setting a floor on the cap rate (the '4'), you ensure you aren’t overpaying. By demanding growth (the '3'), you ensure the asset keeps up with inflation. By insisting on cash flow (the '2') and accounting for losses (the '1'), you protect your downside.
Consider a scenario where you are looking at a retail strip center. The asking price implies a 5.5% cap rate. That clears the '4' hurdle easily. But when you look closer, the leases are fixed with no CPI adjustments for five years. That kills the '3' growth component. Suddenly, the deal looks less attractive because you’re relying solely on initial yield rather than growing income. The rule highlights the weakness immediately.
Applying the Rule: A Step-by-Step Example
Let’s put this into practice with a hypothetical industrial warehouse in New Zealand. We’ll walk through the calculation to see if it passes the test.
| Metric | Target (Rule) | Actual Deal Data | Verdict |
|---|---|---|---|
| Cap Rate | ≥ 4.0% | 6.2% | Pass (High Yield) |
| Rent Growth | ≈ 3.0% | Fixed leases, 0% growth | Fail (No Hedge) |
| Cash-on-Cash | ≥ 2.0% | 1.5% | Borderline (Low Margin) |
| Vacancy/Credit | 1.0% Deduction | 10% Market Vacancy | Fail (High Risk) |
In this example, the property fails three out of four checks. The high cap rate is tempting, but the lack of rent escalation clauses means you lose purchasing power over time. The low cash-on-cash return leaves little room for error if interest rates rise. And the market vacancy rate is double the safe assumption. A savvy investor using the 4-3-2-1 lens would either negotiate a lower price to boost the cap rate and cash flow, or pass entirely.
Nuances: When the Rule Doesn’t Fit Perfectly
No rule is universal. The 4-3-2-1 guideline assumes a "core" or "core-plus" investment strategy-buying stable assets in established locations. It does not apply well to development projects or distressed assets. For instance, if you are buying a land bank for future rezoning, you won’t have any income today, so the cap rate and cash-on-cash metrics are irrelevant. Similarly, in ultra-low interest rate environments, institutional buyers might accept sub-4% cap rates for trophy assets in prime global cities like London or Singapore, betting heavily on the '3' (growth) and '1' (scarcity) factors instead.
Also, consider the debt structure. The '2' cash-on-cash return is highly sensitive to leverage. If you borrow 80% of the purchase price, your cash-on-cash return might be negative initially due to high debt service, even if the property is healthy. In such cases, adjust the expectation: maybe you target 0% cash-on-cash in exchange for higher leveraged returns on equity later. The key is understanding *why* you are deviating from the standard.
Common Pitfalls to Avoid
Even with a solid framework, investors make mistakes. Here are the most common traps:
- Ignoring the Cost of Capital: The 4% cap rate floor is arbitrary if your cost of funds is 7%. If you’re borrowing at high rates, a 4% cap rate means you’re losing money every day you hold the asset. Always compare the cap rate to your weighted average cost of capital (WACC).
- Overestimating Growth: Assuming 3% growth is fine, but don’t assume it happens automatically. Check lease structures. Are there CPI-linked escalations? Or are you hoping for market re-leasing gains? Hope is not a strategy.
- Underestimating Expenses: The '1' vacancy allowance is separate from operating expenses. Make sure your NOI calculation already deducts maintenance, insurance, taxes, and management fees. If you calculate NOI incorrectly, your cap rate will be artificially inflated, tricking you into thinking the deal meets the '4' threshold when it doesn’t.
Final Thoughts on Using the 4-3-2-1 Rule
Use the 4-3-2-1 rule as your first line of defense, not your final verdict. It filters out the obvious mismatches between price and performance. It reminds you that real estate investing is a balancing act between yield, growth, liquidity, and risk. When a deal hits all four marks, you’ve found a robust candidate worthy of detailed due diligence. When it misses, you save yourself weeks of wasted effort.
As markets shift-interest rates change, supply chains disrupt, and remote work alters office demand-the specific numbers might tweak slightly. Maybe you start targeting a 5% cap rate floor in a volatile market, or accept 1% cash-on-cash in a high-growth zone. The principles remain constant, but the thresholds should adapt to your local context and risk tolerance. Keep the framework flexible, keep your eyes open, and always let the math lead the emotion.
Is the 4-3-2-1 rule applicable to residential real estate?
Not directly. Residential real estate is primarily valued based on comparable sales (comps) rather than income generation. While landlords care about yields, the primary driver of home prices is buyer sentiment, location desirability, and mortgage availability, not just the rental income stream. The 4-3-2-1 rule is specifically designed for income-producing commercial assets like offices, retail, and industrial buildings.
What if my local market has cap rates lower than 4%?
If prime assets in your area trade at 3.5% or lower, you must adjust the first digit of the rule. This usually signals a high-demand, low-supply market where investors are willing to accept lower yields for perceived safety or capital appreciation potential. In this case, you might relax the cap rate requirement but tighten the requirements for growth and cash flow to compensate for the lower entry yield.
How does leverage affect the cash-on-cash return part of the rule?
Leverage magnifies both gains and losses. High leverage can turn a modest property yield into a strong cash-on-cash return if interest rates are low. However, it also increases risk. If interest rates rise, your debt service increases, potentially wiping out that 2% buffer. Always stress-test your cash-on-cash return assuming interest rates rise by 1-2% to see if the deal still holds up.
Can I use this rule for multifamily apartments?
Yes, especially for larger multifamily complexes (e.g., 5+ units) that are treated as commercial investments. For smaller duplexes or triplexes, banks often treat them as residential loans, and valuations may lean more toward comps. But for institutional-grade apartment blocks, the 4-3-2-1 framework is highly relevant for assessing income stability and yield.
Does the rule account for tax benefits like depreciation?
No, the basic 4-3-2-1 rule focuses on pre-tax cash flow and yield. Tax implications, such as depreciation shields in some jurisdictions or different tax treatments in New Zealand versus the US, vary wildly. You should perform a separate after-tax analysis. The rule gives you a pre-tax sanity check; taxes come later in the detailed modeling phase.